Key points
- If the flat's remaining lease lasts until the youngest buyer using CPF turns 95, you can use CPF up to the lower of the price or the valuation.
- If it does not, the CPF you can use is pro-rated, so you will need more cash.
- Below 20 years of remaining lease, CPF Ordinary Account savings cannot be used at all.
- The HDB loan and the Enhanced CPF Housing Grant are pro-rated in the same way.
Many buyers look at older resale flats because they are bigger and cheaper per square foot. That can be a smart move. But before you fall in love with a flat, check one number first: the remaining lease. It decides how much of your CPF you can put into the purchase, and that changes how much cash you need.
The one rule that matters: age 95
CPF Board looks at whether the flat's remaining lease can cover the youngest buyer who is using CPF until they turn 95.
- If it can, you can use your CPF Ordinary Account savings up to the lower of the purchase price or the valuation.
- If it cannot, you and your co-owners can still use CPF, but only up to a percentage of that amount. The shorter the lease compared with what is needed, the lower the percentage.
The idea behind the rule is simple. CPF is meant to help you own a home that lasts through retirement, so CPF limits how much you can put into a flat whose lease runs out before you do.
An example: the cheaper flat that cost more cash
Here is a scenario we see often. The numbers are rounded to keep it simple.
A young couple, both 30, find a 4-room resale flat for $450,000. The valuation comes in at $450,000 too, so no COV. It is $40,000 cheaper than a newer flat a few blocks away, and the layout is bigger. Their plan is simple: use the housing grant and CPF for the downpayment, take an HDB loan for the rest, and pay the monthly instalments fully from CPF. No cash needed.
What they did not check was the remaining lease. The flat has 55 years left. At 30, they need 65 years of lease to reach age 95. The lease falls 10 years short, so everything gets pro-rated.
| What they planned | What actually applied | |
|---|---|---|
| CPF they can use for this flat | Up to $450,000 | About $350,000 (around 78%) |
| HDB loan | Up to 75% of the price | Lower, because the loan limit is pro-rated too |
| Enhanced CPF Housing Grant | The full amount for their income | Pro-rated, so a smaller grant |
| Monthly instalments | All from CPF | Cash, once the CPF limit is used up |
The result: a bigger downpayment upfront, a smaller grant, and about $100,000 more to pay in cash over the life of the loan once their CPF limit for the flat runs out. They only found this out after committing to the flat, when the numbers for that specific unit came back. The $40,000 saving on the price was wiped out several times over.
The lesson: compare flats on the cash you will actually need, not just the asking price. Two flats at a similar price can need very different amounts of cash, purely because of the lease.
How we worked out the CPF figure: the share of CPF you can use moves from 0% at 20 years of remaining lease to 100% at the lease needed to reach 95. Here that is (55 − 20) ÷ (65 − 20), or about 78% of $450,000. CPF Board's own figure may differ slightly, because it uses your exact birth date and purchase date.
When CPF cannot be used at all
If the remaining lease is below 20 years, your CPF Ordinary Account savings cannot be used for the purchase. Flats this old are rare on the resale market, but it is worth knowing where the line is.
It affects your loan and grant too
The same age 95 test shows up in two other places:
- HDB housing loan. If the remaining lease does not cover the youngest applicant to 95, the loan-to-value limit is pro-rated down from 75%.
- Enhanced CPF Housing Grant. The flat must cover the youngest core member to 95 for the full grant. Otherwise the grant is pro-rated.
So with an older flat, three things can shrink at the same time: the CPF you can use, the loan you can take and the grant you receive. The gap has to be paid in cash.
How to plan before you buy
- Check the real remaining lease on HDB Map, not just the year the block was built.
- Do the age 95 test for the youngest buyer who will use CPF.
- Work out the cash you need after the CPF limit, the loan limit, any cash over valuation and fees.
- Think about the next sale. The buyers of your flat in 10 years will face the same rule, with a shorter lease. See what affects your flat's value.
Our CPF calculator gives you a rough figure in a minute. It is a guide only, because the exact amount depends on details like your exact birth date and the purchase date.
A real case: she checked after the option fee
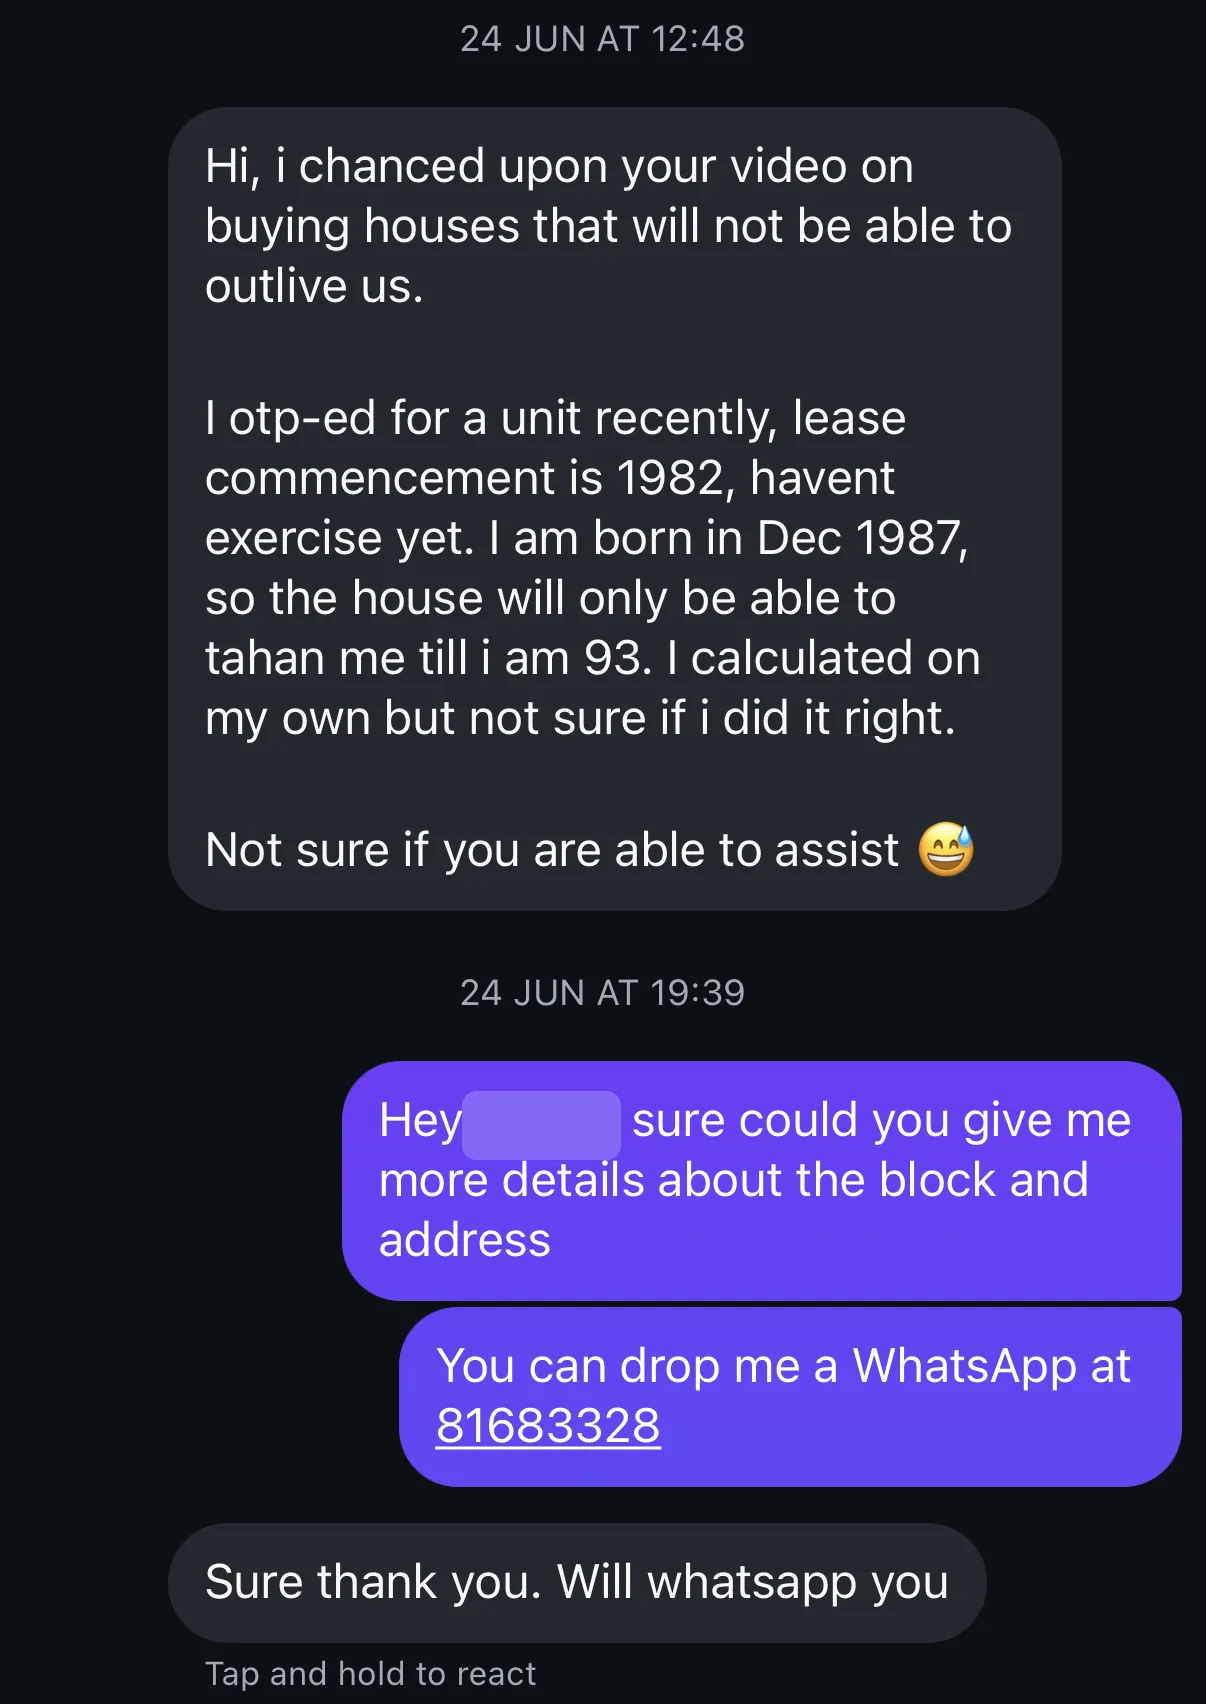
In June, a buyer messaged us on Instagram after watching one of our videos on flats that may not outlive their owners. She had already been granted an Option to Purchase for a flat whose lease started in 1982, but had not exercised it yet. Born in December 1987, she worked out that the lease would only last until she was 93, and she was not sure if her sums were right.
Her maths was right, and it put her just short of the age 95 line. At 38, she needs about 57 years of lease to reach 95, and the flat has about 55 left. So her CPF usage and any grant would be pro-rated. By the same formula, she could use around 95% of the usual CPF amount. A small gap, but one that has to be paid in cash and planned for before exercising the option, not after.
We went through the block and her numbers with her on WhatsApp, so she could make the decision with the full picture. She went ahead with her purchase knowing what to expect.
If you have already paid an option fee on an older flat, check the lease before you exercise it. Our CPF calculator gives a rough figure in a minute, and we are happy to check the exact numbers with you.
Sources: CPF Board and HDB, as of November 2026. Rules can change, so check the latest on cpf.gov.sg and hdb.gov.sg before you commit.
Frequently asked questions
Can I use CPF to buy an HDB flat with less than 60 years of lease left?
Yes, as long as the remaining lease is at least 20 years. If the lease does not cover the youngest buyer using CPF until age 95, the amount of CPF you can use is pro-rated, so you will need more cash.
How do I check the remaining lease of an HDB flat?
Look up the lease commencement date on HDB Map. HDB flats have 99-year leases, so the remaining lease is 99 years minus the years since the lease started.
Does the age 95 rule affect the HDB loan and housing grants?
Yes. If the remaining lease does not cover the youngest applicant to age 95, the HDB loan-to-value limit is pro-rated down from 75%, and the Enhanced CPF Housing Grant is pro-rated too.
Want help with your own numbers?
Every situation is different. Message us and we will work through yours, with no obligation.